


Commercial Property Loans in Melbourne
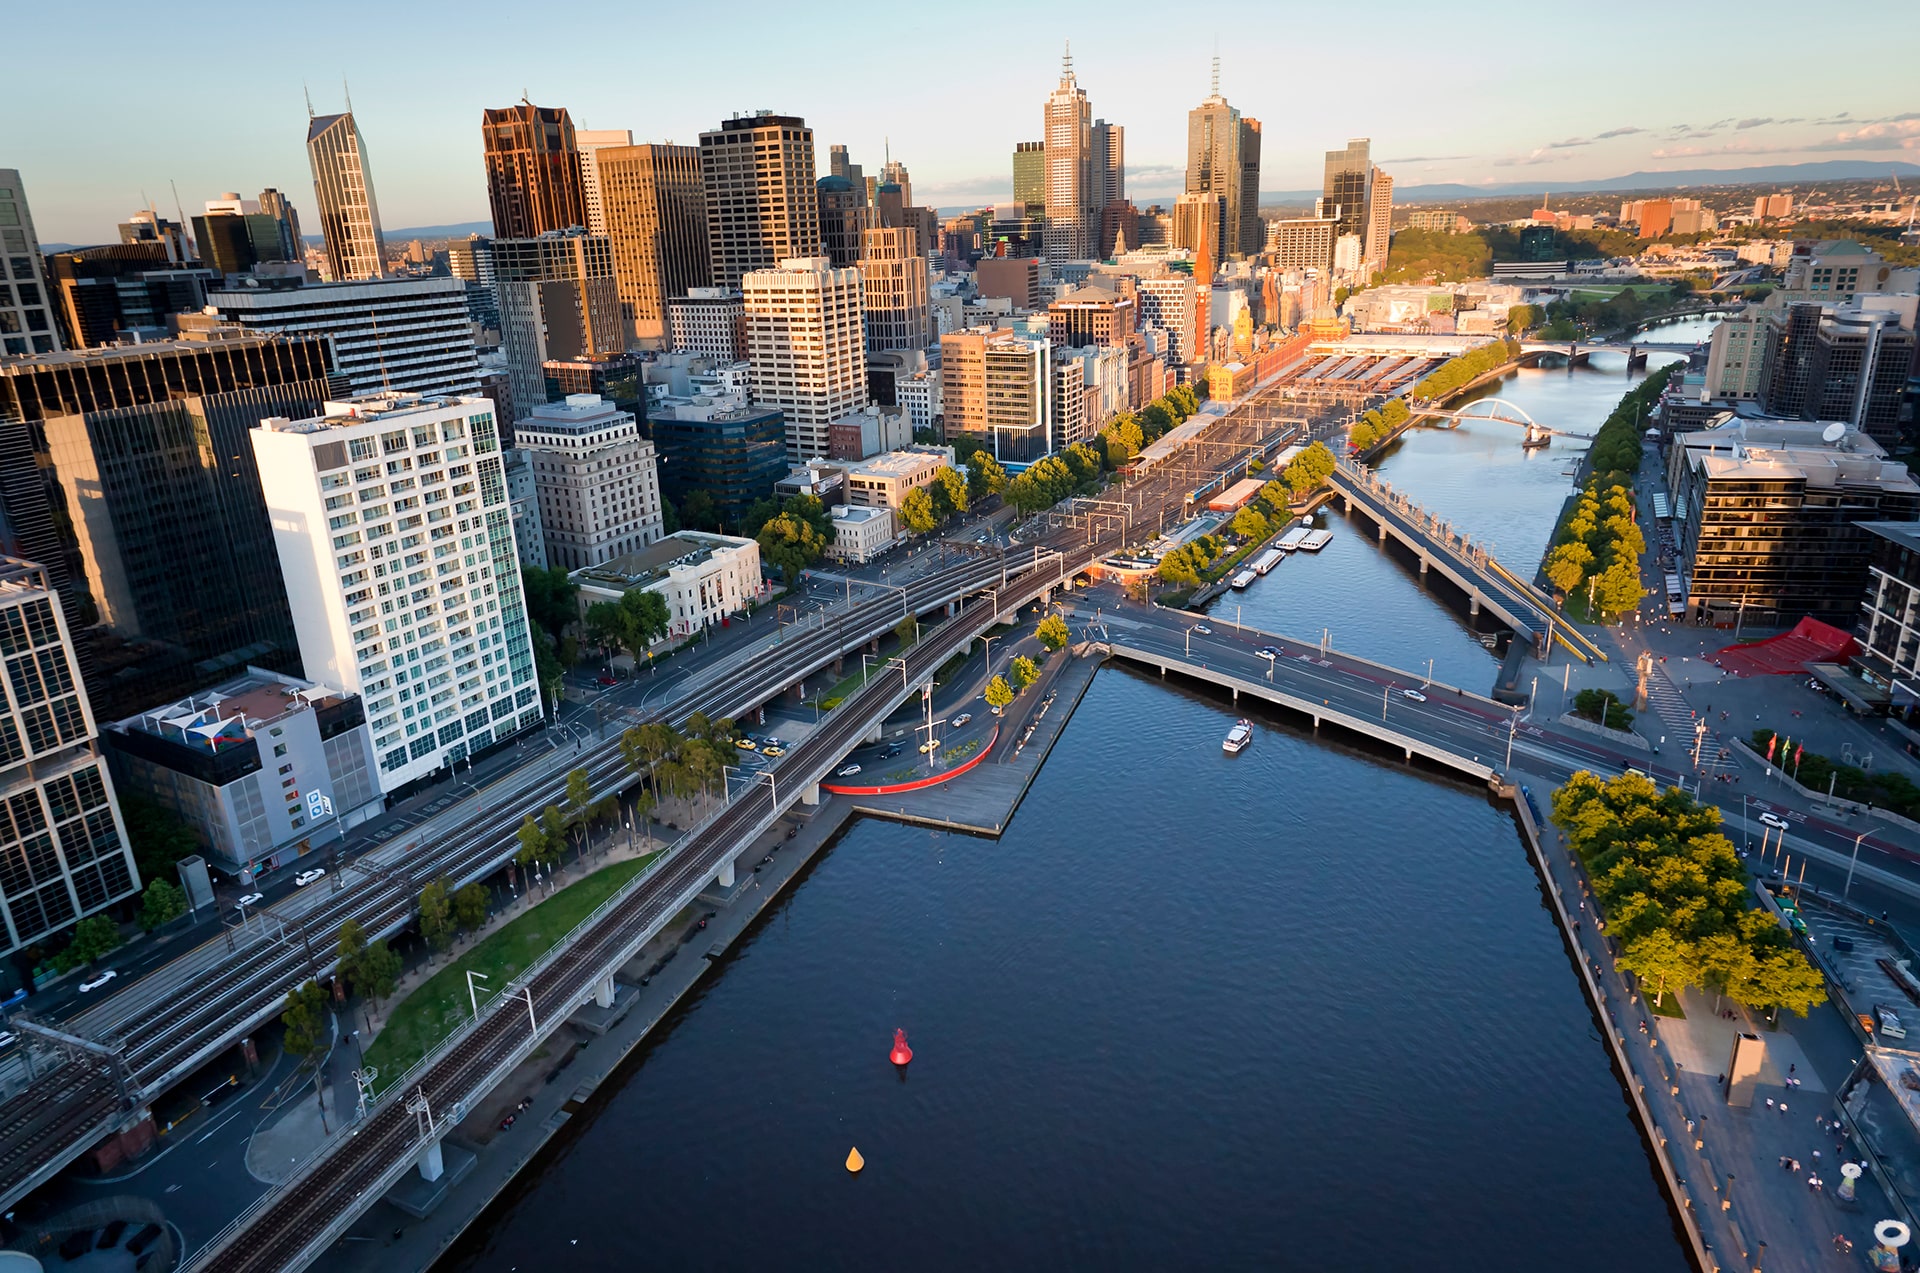
Melbourne’s commercial property market isn’t the same as Sydney or Brisbane, but it also isn’t uniform across the city.
Lenders read a warehouse in Truganina very differently from a medical suite in Box Hill or a CBD office floor. Getting commercial property loans in Melbourne right means matching your deal to the lender who wants it.
Melbourne property, financed by experts who know the area
That’s what we do at Inovayt. From our office at Level 4/550 Spencer Street in West Melbourne, we compare Melbourne commercial property finance across more than 40 lenders and structure loans for owner-occupiers and investors alike.
Why local buyers work with us:
- 40+ lender comparison across banks, commercial and specialist lenders
- Real Melbourne precinct knowledge, not generic advice
- A local office you can sit down in
- Structuring for both owner-occupiers and investors
Get the most competitive rate from 40+ Lenders
Let us do the hard work for you. Access to Australia’s top lenders means we can find and compare the best deals for your business and personal financial needs.



Melbourne Commercial Property Loans: Lending Precincts
Lender appetite shifts suburb by suburb. Here’s a quick read on the main commercial precincts we finance across.
- CBD & city fringe office: Larger deals, more scrutiny. Vacancy is high right now, so lenders look closely at tenant quality and building grade.
- Inner north (Fitzroy, Collingwood, Brunswick): Warehouse conversions and mixed-use. Character stock lenders like it when the numbers stack.
- St Kilda Road & South Melbourne: Established office and medical corridor. Steady demand, well understood by lenders.
- Western industrial (Laverton, Truganina): Modern logistics and warehousing. Strong occupier demand keeps lenders interested.
- South-east industrial (Dandenong, Clayton): Melbourne’s tightest industrial pocket. Clean owner-occupier deals here are among the easiest to fund.
- Eastern & medical (Box Hill, Ringwood, Camberwell): Medical, childcare and defensive assets. Long leases make these attractive to lenders.

What our clients say


The Current Melbourne Market
Knowing where the market sits helps you and your lender price a deal sensibly.
Melbourne’s CBD office vacancy was 19.7% in Q1 2026, representing 1.1 million square metres of unoccupied stock, according to JLL. That’s a tenant’s market, and lenders factor it in when valuing office assets.
Industrial tells a different story. CBRE reported Melbourne industrial vacancy at 4.7%, with net effective rents rising 1.2% quarter-on-quarter for the first time in a year. The south-east remains the tightest pocket in the city.
The takeaway is that property type has a big impact in Melbourne right now. Well-located industrial and medical assets are far easier to finance than secondary CBD offices. We help you read which side of that line your purchase sits on.

Victorian Duty & Tax: What Melbourne Buyers Must Know
Victoria is part-way through a major change to how commercial and industrial property is taxed, and it affects your numbers.
The state is transitioning away from stamp duty for commercial and industrial properties, replacing it with an annual Commercial and Industrial Property Tax (CIPT).
Under the reform, a property enters the system at its next sale on or after 1 July 2024. The buyer pays stamp duty one final time, and the property then sits in CIPT permanently.
There’s a built-in delay before the annual tax starts. CIPT is payable 10 years after the property enters the reform, so the first properties won’t begin paying until the mid-2030s. To help with the final duty payment, eligible purchasers can access a government transition loan, avoiding an upfront lump sum.
The rules have details worth checking before you sign, so confirm your position with the Victorian State Revenue Office. Our VIC stamp duty calculator helps you estimate the one-off duty on your entry transaction, and we’ll help you understand where CIPT fits into your longer-term hold.
Why Melbourne Buyers Use a Broker
In Melbourne, the right lender matters as much as the right rate. Because appetite varies so much by precinct, two lenders can look at the same Dandenong warehouse or Box Hill medical suite and land in very different places.
A single bank only shows you its own view. As a commercial finance broker in Melbourne, we know which lenders back western logistics, which prefer defensive medical income and which will still consider a CBD office deal in the current market. That local read can be the difference between an approval and a knockback, and between an average structure and one built for your goals.
We take care of the legwork and the lender conversations, so you can focus on the property itself.

Ready to Finance Your Melbourne Commercial Property?
You don’t have to work out which lender suits your precinct, or work through Victoria’s changing tax rules alone. We’ll compare your options across 40+ lenders and structure the loan around your goals, explaining every step in plain English.
If you’re also planning a build, our construction loan broker in Melbourne service works the same way.
Contact us or drop into our West Melbourne office to talk through your Melbourne commercial property loan.
Helpful resources

Business Finance Guide
Our business finance guide unpacks everything you need to know about financing your business.
Commercial Property Loans Melbourne – FAQs
Often, yes, though it depends on the transaction. Many commercial sales include GST, but some qualify as a “going concern” and are GST-free. It affects your cash needs at settlement, so confirm the GST treatment with your accountant before you sign.
In many cases, yes. Using equity in your home or another property can reduce the cash you need upfront for a commercial purchase. We’ll help you work out if that structure suits your situation and your borrowing goals.
Many Melbourne buyers purchase commercial property through a company or trust for tax and asset-protection reasons. The right structure depends on your circumstances, so it’s worth a conversation with your accountant and us together before you commit.
Lenders value commercial property on its income and lease profile, and comparable sales are only part of the picture. A strong tenant on a long lease usually supports a higher valuation. If the valuation comes in below your contract price, you may need to cover the gap.
It varies by property type and lender. For full deposit and LVR detail, see our general commercial property loan breakdowns, then talk to us about your specific commercial property finance in Melbourne.
Find an Inovayt Commercial broker near you
Our team of experienced commerical brokers help you discover the right financial solutions for you and your business, so you can put your business in the best possible situation to grow, while having piece of mind.
Our team of experienced commerical brokers help you discover the right financial solutions for you and your business, so you can put your business in the best possible situation to grow, while having piece of mind.
Our team of experienced commerical brokers help you discover the right financial solutions for you and your business, so you can put your business in the best possible situation to grow, while having piece of mind.
Our team of experienced commerical brokers help you discover the right financial solutions for you and your business, so you can put your business in the best possible situation to grow, while having piece of mind.
Why Choose Inovayt

Simple
We understand that managing and reaching your financial goals is an ongoing process. Our experienced team can help you with all types of financial solutions with little stress.

Flexible
We understand that everyone has different needs, schedules and availability. We’re happy to meet face to face, over the phone or online at a time that suits you.

Solutions-driven
Our end-to-end financial solutions can support you throughout any stage of your life journey. It’s never too early to start planning for a comfortable retirement.
