


Review where you are now
We look at your existing home loan, estimated property value, income, commitments and what you want from your next property.

for a bigger home
As your needs change, your family grows and you’ve got more perspective on life, we’ll help you reach your new enough.
When you feel like it’s time to expand, we’ll help you leverage the equity in your existing home so you can buy a place with a bit more room to move.
You know you need more from your next home. The harder part is working out how to get there.
How much equity can you use? How much can you borrow? Should you sell first or buy first? How do you make the move without putting unnecessary pressure on your finances?
An Inovayt mortgage broker will help you understand your options and build a finance strategy around your next move.
Buying your next home isn’t always easier than when you bought your first. Sure, you’ve been through the experience before, but now, because you own a home with a mortgage and potentially have significant equity in that home you have a lot more variables to consider.
Should you sell first so you know exactly how much money you have available to buy? Or is it better to buy first so you don’t miss the right home? Is bridging finance a good idea? And what would your repayments look like after the move?
We help you put the numbers and scenarios side-by-side so you can weigh up the benefits and make an informed decision that’s right for you.
Let us do the hard work for you. Access to Australia’s top lenders means we can find and compare the best deals for your business and personal financial needs.


We will help you estimate the equity available in your existing property and how it can contribute towards your next purchase.

We assess your borrowing capacity, existing commitments and likely repayments to help establish a realistic budget for your next home.

We will model the different scenarios, including bridging finance where appropriate, so you can understand the financial impact before deciding.
Your existing home is one of the biggest factors in determining what comes next.
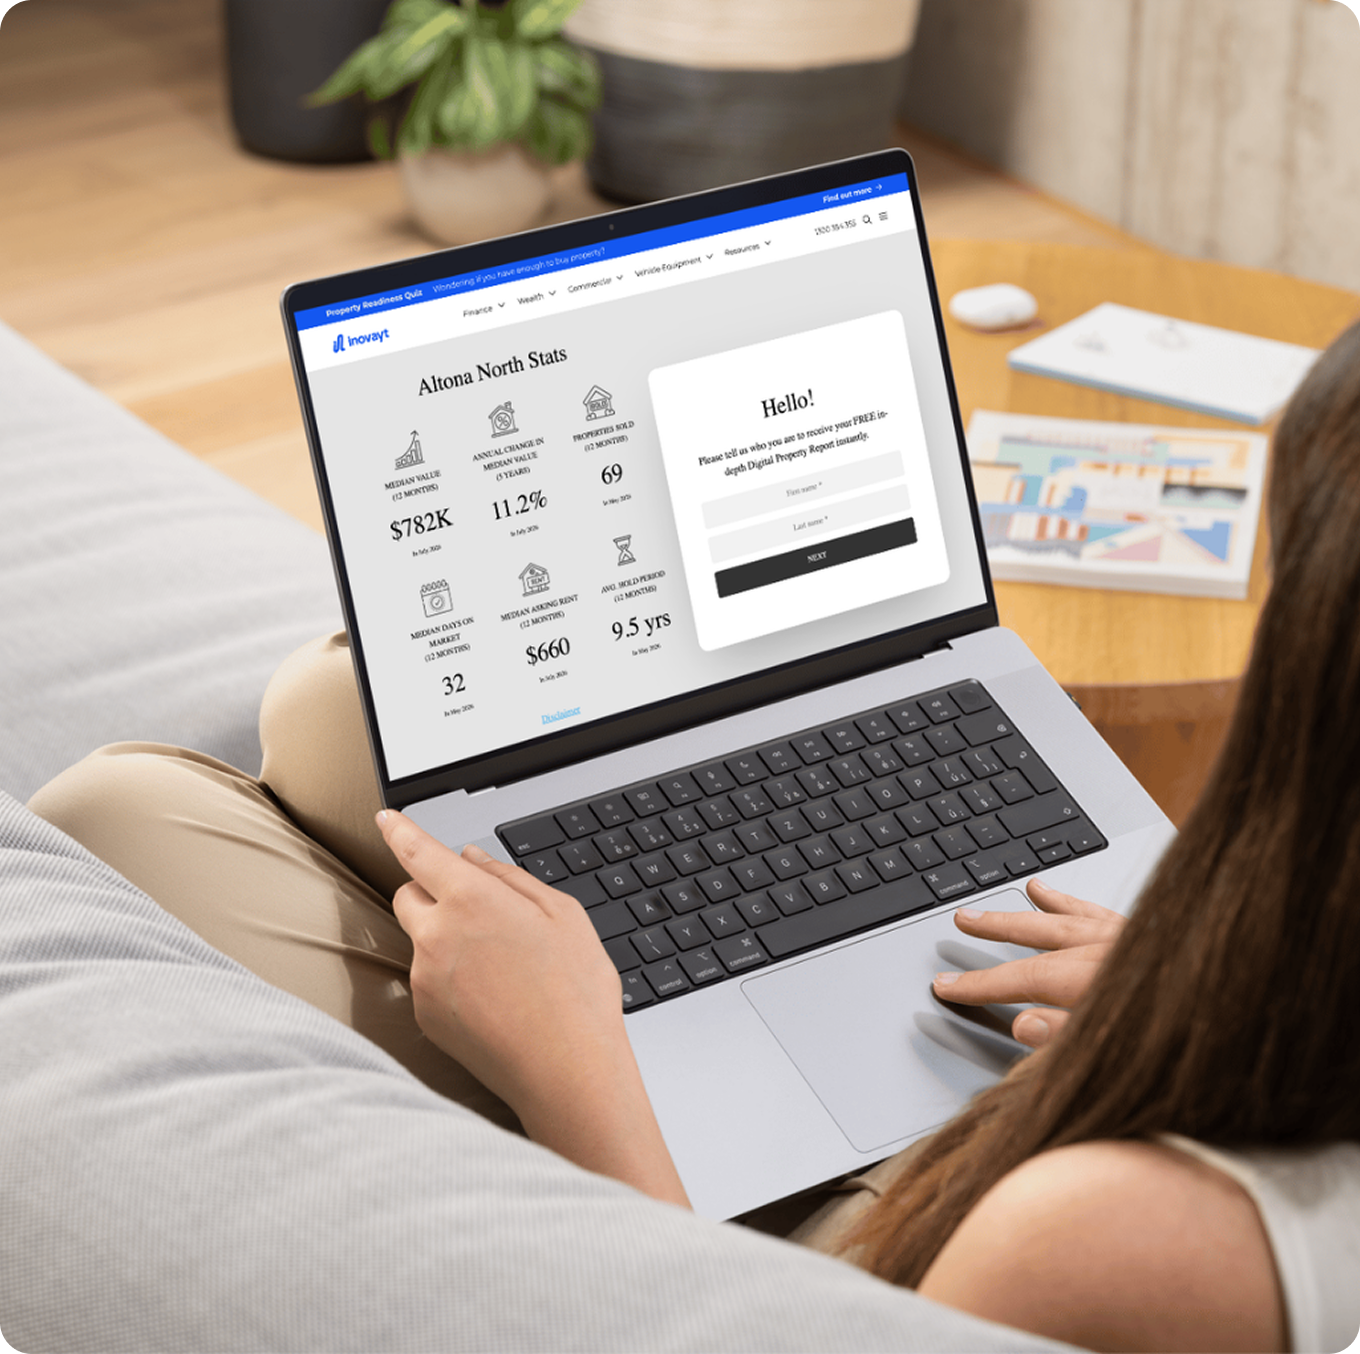
Inovayt’s free Property Report gives you access to useful property and market information, including an estimated property value based on available sales and market data.
It is also a useful place to start the conversation with your broker about your existing equity and next-home options.
The journey to a larger home shouldn’t feel like an uphill battle. Here is a simple, four-step process to help you move with confidence:
We look at your existing home loan, estimated property value, income, commitments and what you want from your next property.
We help establish how much usable equity you have and what you can potentially borrow for your next purchase.
Sell first? Buy first? Bridging finance? Keep the existing property? We will model all the relevant scenarios for you and talk through the pros and cons for each.
Once you know how you want to proceed, we compare suitable lending options and manage the finance process through approval and settlement.
It’s one of the biggest decisions for an upsizer, and there are genuine trade-offs on both sides.
You have greater certainty around your available funds and next-home budget.
But you may need temporary accommodation or feel pressure to find your next property quickly.
You know you have the right new home before selling where you live now.
But you need a clear plan for funding the transition and managing the period before your existing property settles.
For some borrowers, bridging finance is a useful way to fund the gap between purchasing a new property and selling the existing one.
It isn’t suitable for everyone. We will help you understand how the numbers work in your situation so you can compare it with other options.
John and Steph had outgrown their home but weren’t sure how to manage buying and selling at the same time.
After reviewing their position, we helped them understand the equity available in their existing property and gave them a number of options to consider.
Because they wanted the certainty of securing their next home before selling, bridging finance became part of how we helped them manage the gap between buying their new home before selling their old place.
Instead of trying to perfectly time two transactions, they had a plan for making the move into a home that gave their family enough room for what came next.
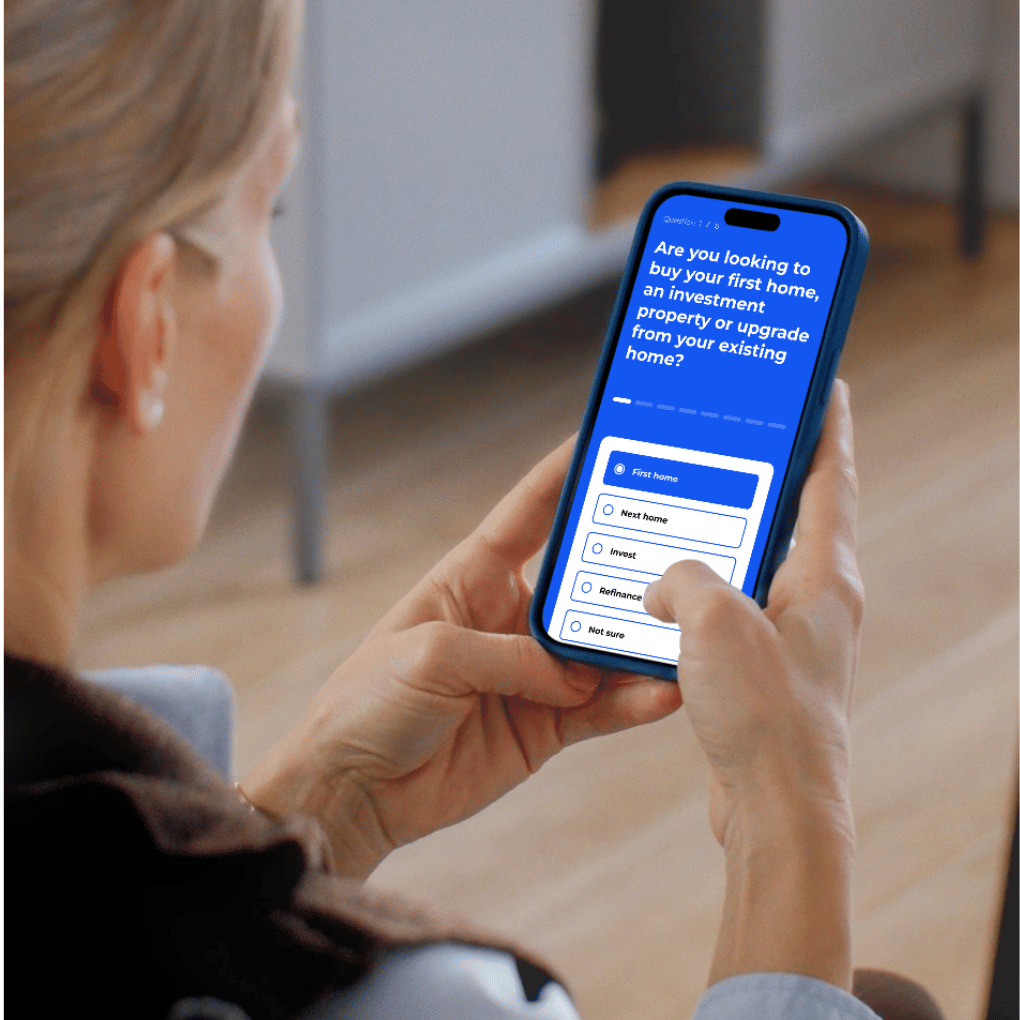
Take our Property Readiness Quiz to get a quick snapshot of your current position and recieve some practical next steps.
It takes less than five minutes.
Equity is broadly the difference between your property’s value and the amount owing against it. The amount you can actually use towards another purchase usually depends on the lender’s requirements and your wider financial position.
There are a few variables here. It is important to consider your finances, the current property market, your tolerance for risk and what your actual priorities are. We can help make sense of all the options so you have a better understanding of the implications to both your finances and your lifestyle.
Bridging finance is a short-term lending option that exists to help fund the gap between buying your next home and selling your existing property. Eligibility and suitability vary, so it’s important to assess the numbers first.
Potentially. Depending on your equity, borrowing capacity and lender requirements, some of the equity in your existing property may be available to support your next purchase.
Sometimes restructuring your existing lending forms part of the strategy; sometimes it doesn’t. We will review your current loan alongside your next purchase rather than treating the two decisions separately.
Reach out to our team of experts today. We’ll show you how easy it can be to get into a bigger home and start living the life you want to live.
(Hint. We’re tipping you’re closer than you think.)