


Review your current position
We look at your income, expenses, existing property, loans, equity and investment objectives.

to grow your property portfolio
Investing shouldn’t be about the endless pursuit of more. It’s about understanding how you want to live. Because that’s how you find your enough: the specific wealth required to live the life you actually want.
That’s where Inovayt steps in.
Property investment isn’t just about how much you can borrow today.
The way you structure your lending will affect your cash flow, borrowing capacity and ability to make your next move.
Whether you’re buying your first investment property or adding to an existing portfolio, an Inovayt mortgage broker will help you understand your borrowing position, compare lenders and structure your finance around where you want to go.
Getting one investment loan approved is one thing.
Building a lending structure that still works if you want to buy again is another.
Your existing debt, usable equity, cash flow, loan structure and choice of lender all affect what becomes possible next.
That’s why we look beyond simply finding a competitive rate.
We help you understand your borrowing position and compare finance options in the context of your broader property goals so your lending gives you enough flexibility for what comes next.

Different lenders assess investors and their existing portfolios differently. We review your financial position to help establish what is possible now and consider how today’s lending decision will affect future borrowing.

If you have equity in an existing home or investment property, we will help you understand how it can be leveraged to enable another purchase.

Principal and interest, interest-only, offsets, refinancing and lender choice all affect your cash flow and flexibility. We help you compare relevant structures rather than defaulting to a one-size-fits-all loan.
Let us do the hard work for you. Access to Australia’s top lenders means we can find and compare the best deals for your business and personal financial needs.

Interest-only repayments reduce your required repayments for a specific period and suit some investment strategies more than others.
Whether it makes sense depends on your cash flow, objectives, total cost and longer-term lending plan.
An offset account allows eligible borrowers to hold accessible cash while reducing the amount of loan balance on which interest is calculated.
The right setup depends on how your investment and non-investment debt is structured.
If your existing property has increased in value, you may be able to access some of the available equity to help fund another purchase.
Before doing so, it’s important to understand the impact on your overall debt, repayments and borrowing position.
Building your investment portfolio doesn’t need to be complicated. Here is a simple 5 step process to to help you on your way sooner.
We look at your income, expenses, existing property, loans, equity and investment objectives.
We assess your borrowing position and potential usable equity across suitable lenders.
We consider loan structure, lender options, repayments and flexibility in the context of what you’re trying to achieve.
When you’re ready to purchase or refinance, we manage the application and lending process through to settlement.
Your lending needs can change as your portfolio and financial position change. Reviewing the structure before the next purchase can help identify issues early.
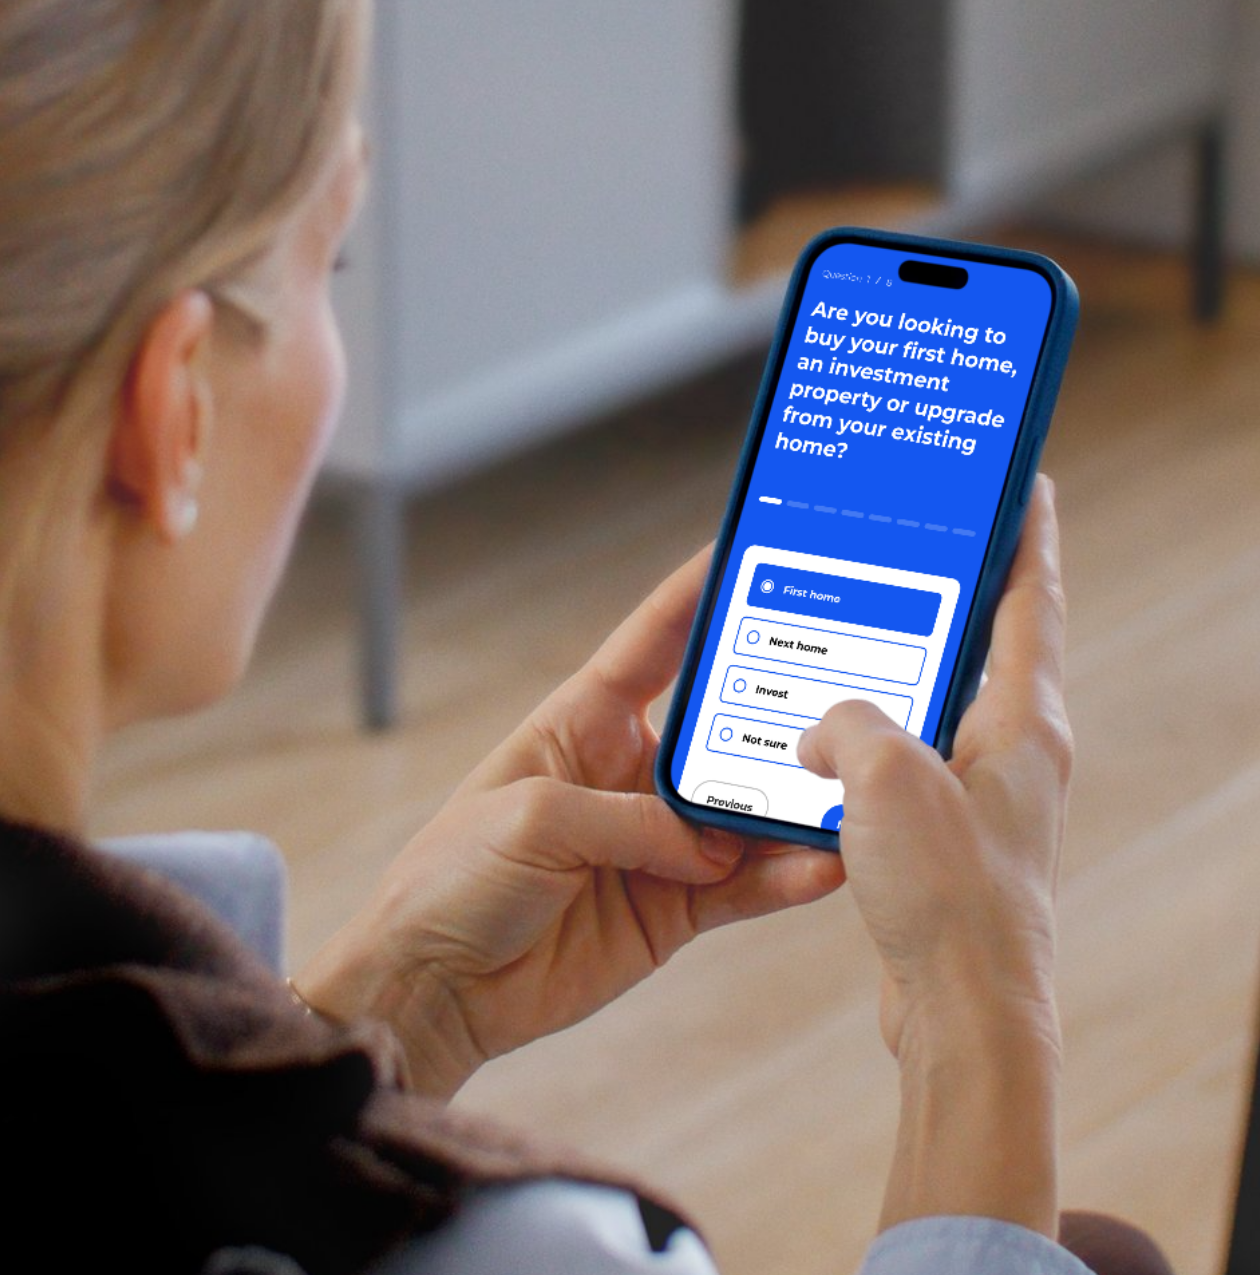
The Property Readiness Quiz gives you a quick snapshot of your current position and practical next steps based on your circumstances.
It takes less than five minutes.
Investment borrowing capacity depends on your income, expenses, existing debts, property portfolio, expected rental income and the lender’s assessment criteria. Every lender makes their decisions based on a different mix of criteria, which means they can reach different outcomes, which is why comparing beyond a single lender is always worthwhile.
Potentially. If you have sufficient usable equity in an existing property and meet lending requirements, it may be possible to use some of that equity towards another purchase.
Neither is automatically better than the other. The right structure depends on your objectives, cash flow, overall lending position and longer-term strategy. We can help you compare the lending implications of each.
Reviewing your existing loans before another purchase is always a good idea. It will help identify whether your current lender and structure still suits your plans. Refinancing isn’t always required, but it is worth considering as part of your wider strategy.
Yes. Lending decisions can intersect with tax, investment and broader financial considerations. Where appropriate, your broker can work alongside your other professional advisers while remaining focused on the credit and lending strategy.
Reach out to our team of experts today. We’ll show you how easy it can be to grow your property portfolio and start living the life you want to live.
(Hint. We’re tipping you’re closer than you think.)